Deprecated: Function WP_Dependencies->add_data() was called with an argument that is deprecated since version 6.9.0! IE conditional comments are ignored by all supported browsers. in /home/corerepo/public_html/wp-includes/functions.php on line 6260 Nigeria Launches $78.5bn Investment Pipeline at IMF, World Bank Meetings - Core Reporters
Nigeria Launches $78.5bn Investment Pipeline at IMF, World Bank Meetings
…Seeks Reforms to Global Financial System, Job-Creating Growth
By Our Finance Correspondent
Bangkok (Core Reporters) – Nigeria has presented an investment pipeline worth $78.5 billion to international investors and called for reforms to the global financial system to improve access to affordable financing for developing economies.
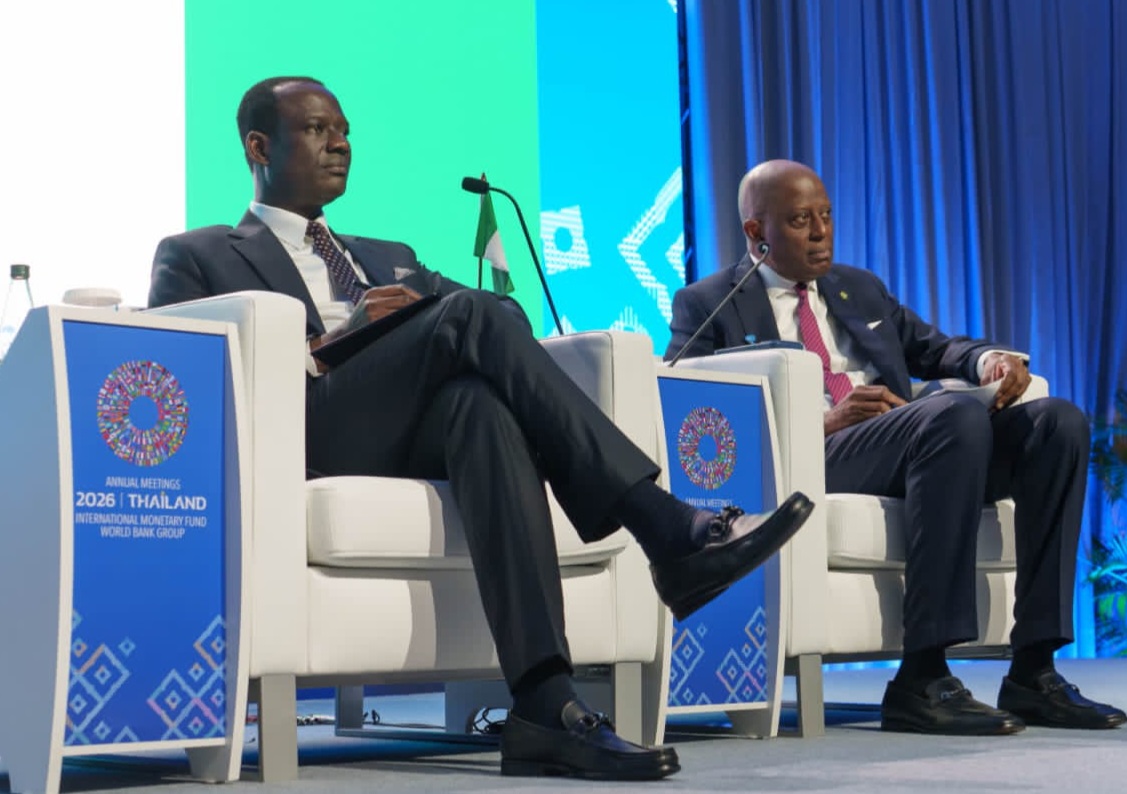
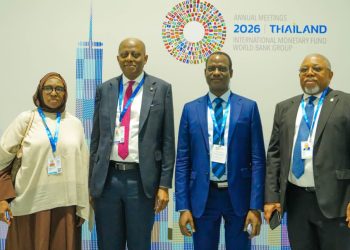
The presentation formed part of Nigeria’s participation in the 2026 Annual Meetings of the International Monetary Fund (IMF) and the World Bank Group in Bangkok, Thailand, where the country’s delegation highlighted progress in economic reforms and stressed the need to translate macroeconomic stability into faster, job-creating growth.
The delegation was led by the Minister of Finance and Coordinating Minister of the Economy, Mr Taiwo Oyedele, and the Governor of the Central Bank of Nigeria, Mr Olayemi Cardoso.
During the meetings, the Nigerian team presented key economic indicators, including second-quarter 2026 economic growth of about 4.4 per cent, four consecutive months of declining inflation, foreign reserves exceeding $55 billion, a tax-to-GDP ratio of 12.5 per cent and public debt estimated at 36 per cent of GDP.
A major highlight was the launch of Projects Nigeria, an initiative featuring 65 bankable projects valued at approximately $78.5 billion.
The initiative attracted expressions of interest from investors in Asia and Europe, signalling potential opportunities for foreign investment in Nigeria’s priority sectors.
Nigeria also secured further engagement with the World Bank Group on power and infrastructure financing through guarantee instruments designed to support investment and project delivery.
The IMF reaffirmed its technical support for Nigeria in areas including fiscal governance, transparency and statistics, while the Japan International Cooperation Agency (JICA), the United States Treasury and the European Union expressed commitments to deepen cooperation with the country.
The meetings also marked the conclusion of Nigeria’s chairmanship of the Group of 24 (G-24), during which the country advanced calls for a quota-based IMF system, fairer credit-rating mechanisms and lower financing costs for developing economies.
Addressing the challenge of employment in a rapidly changing global economy, Oyedele warned that technological advances, particularly artificial intelligence, could drive economic growth without generating sufficient jobs.
He cited projections indicating that about 1.2 billion young people would enter the global labour market over the next 10 to 15 years, while only about 400 million jobs were expected to be available, according to the World Bank.
The minister urged the Bretton Woods institutions to place job creation at the centre of their assessment of economic performance, arguing that macroeconomic stability must translate into tangible opportunities for citizens.
“Stability was the first test. Growth that employs our people is the second,” Oyedele said.
He also reaffirmed the Federal Government’s position against returning to fuel subsidies or multiple exchange rates, maintaining that the government would sustain its reform direction while pursuing stronger economic growth and employment opportunities.
Nigeria’s participation in the meetings underscored its efforts to attract long-term investment, strengthen international partnerships and secure a more equitable global financial architecture capable of supporting sustainable development in emerging economies.